
1. Statement of Accounting Policies
Basis of accounting
In line with section 12 of the Revenue Scotland and Tax Powers Act 2014 (RSTPA), and in accordance with the accounts direction issued by the Scottish Ministers under section 19(4) of the Public Finance and Accountability (Scotland) Act 2000, these financial statements have been prepared conforming to the 2025-26 Government Financial Reporting Manual (FReM) issued by His Majesty’s Treasury. The accounting policies contained in the FReM apply International Financial Reporting Standards (IFRS) as adapted or interpreted for the public sector context. The particular policies adopted are described below. They have been applied consistently in dealing with items that are considered material to the accounts. The accounts are prepared using accounting policies, and where necessary, estimation techniques which are judged to be most appropriate to the particular circumstances for the purpose of giving a true and fair view regarding the principles set out in International Accounting Standards (IAS) 8 Accounting Policies, Changing in Accounting Estimates and Errors. In accordance with the FReM these accounts have been prepared under the historical cost convention and on a going concern basis, which provides that the organisation will continue in operational existence for the foreseeable future.
Accounting convention
The accounts have been prepared in accordance with the historical cost convention modified to account for fair value of non-current assets. Expenditure has been accounted for on an accruals basis.
New accounting standards
In accordance with IAS 8: Accounting Policies, Changes in Accounting Estimates and Errors, changes to International Financial Reporting Standards (IFRS) that have been issued but not yet effective have been reviewed for impact on the financial statements in the period of initial application. There are no updates to the standards that are considered to be relevant to Revenue Scotland’s Resource Account. IFRS17 (Insurance Contracts) replaced IFRS 4 (Insurance Contracts) and was effective in 2025- 26. It did not impact on the 2025-26 Resource Accounts.
IFRS 18 Presentation and Disclosure in Financial Statements replaces IAS 1 Presentation of Financial Statements and is effective for annual reporting periods beginning on or after 1 January 2027. The impact of IFRS 18 on the public sector continues to be assessed and, at the reporting date, no implementation date had been confirmed for the UK public sector.
Value Added Tax (VAT)
Revenue Scotland is registered for VAT as part of the Scottish Government VAT group registration, which is responsible for recovering VAT on behalf of Revenue Scotland. Revenue Scotland does not provide any chargeable services and therefore output VAT does not apply. Irrecoverable input VAT is charged to the relevant expenditure category. Where VAT is recoverable, the amounts are stated net of VAT.
Property, plant, equipment and intangible assets Recognition
All property, plant, equipment and intangible assets are accounted for as non-current assets unless they are deemed to be held for sale.
Capitalisation
Minor expenditure on equipment and furniture are written off in the year of purchase, as are all other items of a capital nature costing less than £10,000, unless the pooled value of a programme of expenditure on items of a capital nature exceeds £10,000, then this pooled expenditure is capitalised.
Assets under development
Assets under development are shown separately in note 5. Costs are accumulated until the assets is brought into use whereupon it is transferred into the relevant asset class and depreciated.
Staff costs
Where staff have been working on the development, integration and testing of IT software, these costs are included in the amounts capitalised.
Depreciation and Amortisation
Provision for depreciation and amortisation is made to write off the cost of non current assets on a straight-line basis over the expected useful lives of the assets concerned. The expected useful lives of assets are regularly and systematically reviewed to ensure that they genuinely reflect the actual replacement cycle of all assets. Depreciation and amortisation are not charged on assets in the course of development until the month after they are brought into use. The expected useful lives are as follows:
- computer equipment, 3–10 years
- IT and telephony systems, 3–10 years
- office equipment, 3–10 years
- furniture and fittings, 3–15 years.
Asset Valuation
Depreciated and amortised historical cost is used as a proxy for fair value since the assets are low value and have short useful lives. The majority of the intangible assets represent bespoke IT systems and there is no active market for these assets. In accordance with the FReM impairment relating to a consumption of economic benefit or reduction in service potential is taken to the SoCNE.
Financial instruments
As the cash requirements of Revenue Scotland are met through the Scottish Government, financial instruments play a limited role in creating and managing risk. The only financial instruments within the accounts are financial assets in the form of other receivables, and financial liabilities such as trade and other liabilities.
Leases
Revenue Scotland has adopted IFRS 16 including the exemption for short term leases in accordance with the FReM. This standard replaces the previous standard IAS 17. Leases which are considered to be low value or have an expected length of less than a year, are not recognised under IFRS 16 and the related costs are shown in the Statement of Comprehensive Net Expenditure.
Pension costs
Revenue Scotland employees are civil servants who are entitled to be members of the Civil Servant and Others Pension Scheme or the Principal Civil Service Pension Scheme. These are unfunded, multi employer defined benefit schemes in which Revenue Scotland is unable to identify its share of the underlying assets and liabilities. The schemes are accounted for as defined contribution schemes under the multi employer exemption permitted in IAS 19 Employee Benefits. Revenue Scotland’s contribution is recognised as a cost in the year.
Short term employee benefits
The cost of annual leave and flexible working time entitlement earned but not taken by employees at the end of the year is recognised as an accrual of benefits in the financial statements. Employees are permitted to carry forward leave into the following year.
Other receivables
Other receivables are stated at their nominal value.
Trade and other payables
Trade payables are stated at their nominal value.
Provisions for liabilities and charges
A provision is recognised where an outflow of resources is expected because of a past event. These are included within the accounts at the estimated value.
2. Staff costs
| 2025-26 Admin £000 |
2025-26 Programme £000 |
2025-26 £000 |
2024-25 £000 |
|
|---|---|---|---|---|
| Staff costs | ||||
| Wages and salaries | 5,007 | 410 | 5,417 | 4,645 |
| Social security | 667 | 46 | 713 | 511 |
| Pension | 1,405 | 114 | 1,519 | 1,322 |
| Agency | 47 | 0 | 47 | 64 |
| Total staff costs | 7,126 | 570 | 7,696 | 6,542 |
Programme costs incurred relate to staff working on the introduction of SAT, SBSL and ADT. More details on staff numbers and related costs can be found in the Staff Report.
3. Goods and services
Revenue Scotland’s goods and services have been allocated as follows:
| 2025-26 Admin £000 |
2024-25 Admin £000 |
|
|---|---|---|
| Income | ||
| Misc income | (0) | 0 |
| Total income | (0) | 0 |
| Staff-related costs | ||
| Board fees & expenses | 95 | 43 |
| Travel and subsistence | 4 | 5 |
| Training | 19 | 12 |
| Supplies & services | ||
| Legal | 53 | 27 |
| Computer & telephone | 490 | 435 |
| Shared services | 396 | 383 |
| Delegated duties | 372 | 369 |
| Other supplies & services | 122 | 104 |
| Audit fee - external | 116 | 108 |
| Total goods & services | 1,667 | 1,486 |
(1) In the interests of efficiency, effectiveness and economy, Revenue Scotland and the Scottish Ministers are committed to identifying opportunities for shared services. The amount represents costs charged by the Scottish Government for the following functions: - -
- Human Resource management (including, for example: general terms and conditions of service, pay negotiations, pay awards, payroll, pensions, and recruitment for senior civil service posts)
- financial management (Scottish Government finance systems)
- information systems, telephony, information and library service
- estates and facilities management
- internal audit procurement
(2) Delegated duties represent the amounts payable to the SEPA in relation to the duties delegated to them under the Revenue Scotland and Tax Powers Act 2014.
4. Reconciliation of net resource outturn to net funding received
| Notes | 2025-26 £000 |
2024-25 £000 |
|
|---|---|---|---|
| Resource outturn | SoCNE | 10,205 | 8,694 |
| Capital outturn – tangible asset additions | 5 | 23 | 61 |
| Capital outturn – intangible asset additions | 5 | 844 | 1,191 |
| Proceeds from Disposal of assets | SoCF | 0 | 0 |
| Non cash charges – auditor's remuneration | 9 | (116) | (108) |
| Loss on disposal | 5 | 0 | 0 |
| Depreciation | 5 | (39) | (27) |
| Amortisation | 5 | (871) | (639) |
| Revaluation | 5 | 68 | 0 |
| Changes in working capital | SoCF | 19 | (439) |
| Net funding | 10,133 | 8,733 |
5. Non-current assets
Tangible assets
| IT Hardware £000 |
Furniture & fittings £000 |
2025-26 £000 |
|
|---|---|---|---|
| Cost | |||
| At 1 April | 142 | 76 | 218 |
| Additions | 23 | 0 | 23 |
| Impairment reversal | 0 | 0 | 0 |
| Disposal | (48) | 0 | (48) |
| At 31 March | 117 | 76 | 193 |
| Depreciation | |||
| At 1 April | 56 | 66 | 122 |
| Charged in the year | 34 | 5 | 39 |
| Depn Disposal | (48) | (48) | |
| At 31 March | 42 | 71 | 113 |
| Asset financing | |||
| Owned | 75 | 5 | 80 |
| Carrying amount at 31 March | 75 | 5 | 80 |
| IT Hardware £000 |
Furniture & fittings £000 |
2024-25 £000 |
|
|---|---|---|---|
| Cost | |||
| At 1 April | 81 | 76 | 157 |
| Additions | 61 | 0 | 61 |
| Impairment reversal | 0 | 0 | 0 |
| Disposal | 0 | 0 | 0 |
| At 31 March | 142 | 76 | 218 |
| Depreciation | |||
| At 1 April | 34 | 61 | 95 |
| Charged in the year | 22 | 5 | 27 |
| Depn Disposal | 0 | ||
| At 31 March | 56 | 66 | 122 |
| Asset financing | |||
| Owned | 86 | 10 | 96 |
| Carrying amount at 31 March | 86 | 10 | 96 |
Intangible assets
| IT System under development £000 |
IT System £000 |
2025-26 Total £000 |
|
|---|---|---|---|
| Cost | |||
| At 1 April | 0 | 5,937 | 5,937 |
| Additions | 363 | 481 | 844 |
| Transfer | 0 | 0 | 0 |
| Impairment reversal | 0 | 0 | 0 |
| Disposal | 0 | 0 | 0 |
| At 31 March | 363 | 6,419 | 6,781 |
| Amortisation | |||
| At 1 April | 0 | 2,473 | 2,473 |
| Charged in the year | 0 | 871 | 871 |
| Revaluation | 0 | (68) | (68) |
| At 31 March | 0 | 3,276 | 3,276 |
| Asset financing | |||
| Owned | 363 | 3,142 | 3,505 |
| Carrying amount at 31 March | 363 | 3,142 | 3,505 |
Intangible assets
| IT System under development £000 |
IT System £000 |
2024-25 Total £000 |
|
|---|---|---|---|
| Cost | |||
| At 1 April | 125 | 4,621 | 4,746 |
| Additions | 0 | 1,191 | 1,191 |
| Transfer | (125) | 125 | 0 |
| Impairment reversal | 0 | 0 | 0 |
| Disposal | 0 | 0 | 0 |
| At 31 March | 0 | 5,937 | 5,937 |
| Amortisation | |||
| At 1 April | 0 | 1,834 | 1,834 |
| Charged in the year | 0 | 639 | 639 |
| Revaluation | 0 | 0 | 0 |
| At 31 March | 0 | 2,473 | 2,473 |
| Asset financing | |||
| Owned | 0 | 3,464 | 3,464 |
| Carrying amount at 31 March | 0 | 3,464 | 3,464 |
6. Other receivables
| Amounts falling due within one year | 2025-26 £000 |
2024-25 £000 |
|---|---|---|
| Prepaid expenses | 53 | 19 |
| Sundry debtors | 89 | 74 |
| Total receivables within one year | 142 | 93 |
7. Trade and other payables
| Amounts falling due within one year | 2025-26 £000 |
2024-25 £000 |
|---|---|---|
| Trade payables | 19 | 126 |
| Social security and payroll-related | 337 | 260 |
| Accrued short-term employee benefits | 405 | 286 |
| Other accruals | 402 | 461 |
| Total payables within one year | 1,163 | 1,133 |
8. Related party transactions
Revenue Scotland is a Non-Ministerial Office of the Scottish Administration, and it considers that the Scottish Government, its agencies, and non-departmental bodies are related parties within this context. During the year, Revenue Scotland had a significant number of material financial transactions with the Scottish Government and with other entities for which Scottish Government is regarded as the parent Department. This includes receipt of grant in aid funding. Those relating to shared services provided are detailed in note 3 above. In line with RSTPA, section 2, Revenue Scotland has delegated some of its functions relating to SLfT to SEPA. The costs incurred are provided in note 3 above. None of the Board members, key managerial staff or other related parties has undertaken any material transactions with Revenue Scotland during the year.
9. Audit fee
| 2025-26 £000 |
2024-25 £000 |
|
|---|---|---|
| Auditor's fee – resource accounts | 22 | 21 |
| Auditor's fee – devolved taxes account | 91 | 87 |
| Additional 2024-25 Auditor's fee | 3 | |
| Total Auditor’s fees | 113* | 111 |
*2025-26 Audit fee in the above financial accounts is shown as £116k, a £3k variance. This is due to the additional 24/25 auditor’s fee being paid in 2025-26 due to the timing of the charge after the closing of the accounts
Auditor’s remuneration is disclosed as a notional charge and relates to fees notified to Revenue Scotland by Audit Scotland in respect of audit work carried out to the year ended 31 March 2026. All audit fees are paid from the Scottish Consolidated Fund. No non-audit work was carried out by Audit Scotland during the year ended 31 March 2026. 2025-26 includes an additional £3,000 for additional work carried out for 2024-25 but was not charged until the after the conclusion of the accounts.
10. Commitments
Total future minimum payments under contractual commitments are given in the tables below for each of the following periods.
Revenue commitments
| 2025-26 £000 |
2024-25 £000 |
|
|---|---|---|
| Not later than one year | 347 | 338 |
| Between one and five years | 688 | 975 |
| Beyond five years | 0 | |
| Total revenue commitments | 1,035 | 1,313 |
The amounts above are in relation to the contracts for the provision of Revenue Scotland’s tax, finance and call management systems.
Capital commitments
Revenue Scotland had no capital commitments in either 2025-26 or 2024-25 financial years.
11. Events after the reporting period
There are no events after the reporting period which would have an effect on the Annual Report and Accounts for which would require disclosure.
Accounts authorised for issue on 9 October 2026.
Summary financial data
Devolved Taxes 2020-26
| 2020-21 £000 |
2021-22 £000 |
2022-23 £000 |
2023-24 £000 |
2024-25 £000 |
2025-26 £000 |
|
|---|---|---|---|---|---|---|
| LBTT | 517,354 | 807,183 | 847,836 | 784,372 | 899,162 | 952,039 |
| SLfT | 106,528 | 125,248 | 109,699 | 68,372 | 55,938 | 55,478 |
| Penalties and Interest | 138 | 1,245 | 2,797 | 2,714 | 6,457 | 5,492 |
| Total tax revenue | 624,020 | 933,676 | 960,332 | 855,458 | 961,557 | 1,013,009 |
| LBTT 2020-26 | 2020-21 £000 |
2021-22 £000 |
2022-23 £000 |
2023-24 £000 |
2024-25 £000 |
2025-26 £000 |
|---|---|---|---|---|---|---|
| Residential | 259,632 | 418,390 | 464,904 | 421,046 | 485,450 | 522,389 |
| Net ADS | 115,104 | 140,750 | 162,896 | 176,226 | 179,740 | 198,918 |
| Non residential | 142,618 | 248,043 | 220,036 | 187,100 | 233,972 | 230,732 |
| Total LBTT (£000) | 517,354 | 807,183 | 847,836 | 784,372 | 899,162 | 952,039 |
| LBTT 2020-26 | 2020-21 £000 |
2021-22 £000 |
2022-23 £000 |
2023-24 £000 |
2024-25 £000 |
2025-26 £000 |
|---|---|---|---|---|---|---|
| No. of tax returns | 109,170 | 126,350 | 118,990 | 110,830 | 123,950 | 125,346 |
| SLfT 2020-26 | 2020-21 £000 |
2021-22 £000 |
2022-23 £000 |
2023-24 £000 |
2024-25 £000 |
2025-26 £000 |
|---|---|---|---|---|---|---|
| Tax (£000) | 106,528 | 125,248 | 109,699 | 68,372 | 55,938 | 55,478 |
| SLfT 2020-26 | 2020-21 £000 |
2021-22 £000 |
2022-23 £000 |
2023-24 £000 |
2024-25 £000 |
2025-26 £000 |
|---|---|---|---|---|---|---|
| Standard rate tonnage | 1,170,300 | 1,348,600 | 1,179,100 | 693,100 | 551,000 | 451,700 |
| Lower rate tonnage | 618,800 | 680,100 | 684,500 | 607,000 | 550,500 | 379,500 |
| Total tonnage | 1,789,100 | 2,028,700 | 1,863,600 | 1,300,100 | 1,101,500 | 831,200 |
Resource Spend (including programme costs) 2020-26
| 2020-21 £000 |
2021-22 £000 |
2022-23 £000 |
2023-24 £000 |
2024-25 £000 |
2025-26 £000 |
|
|---|---|---|---|---|---|---|
| Income | 59 | 41 | 44 | 1 | 0 | 0 |
| Staff costs | (4,234) | (4,324) | (4,800) | (5,455) | (6,162) | (7,697) |
| Goods & services | (1,651) | (1,638) | (1,568) | (1,467) | (1,476) | (1,666) |
| Programme costs | (30) | 0 | (104) | (377) | (390) | (39) |
| Depreciation & amortisation | (377) | (417) | (432) | (534) | (666) | (871) |
| Revaluation | 0 | 0 | 0 | 0 | 0 | 68 |
| Impairment | 0 | 0 | (49) | 49 | 0 | |
| Provision | 0 | 0 | 0 | 0 | 0 | |
| Loss on Disposal | 0 | 0 | 0 | (49) | 0 | |
| Net operating costs | (6,233) | (6,338) | (6,909) | (7,832) | (8,694) | (10,204) |
Direction by the Scottish Ministers
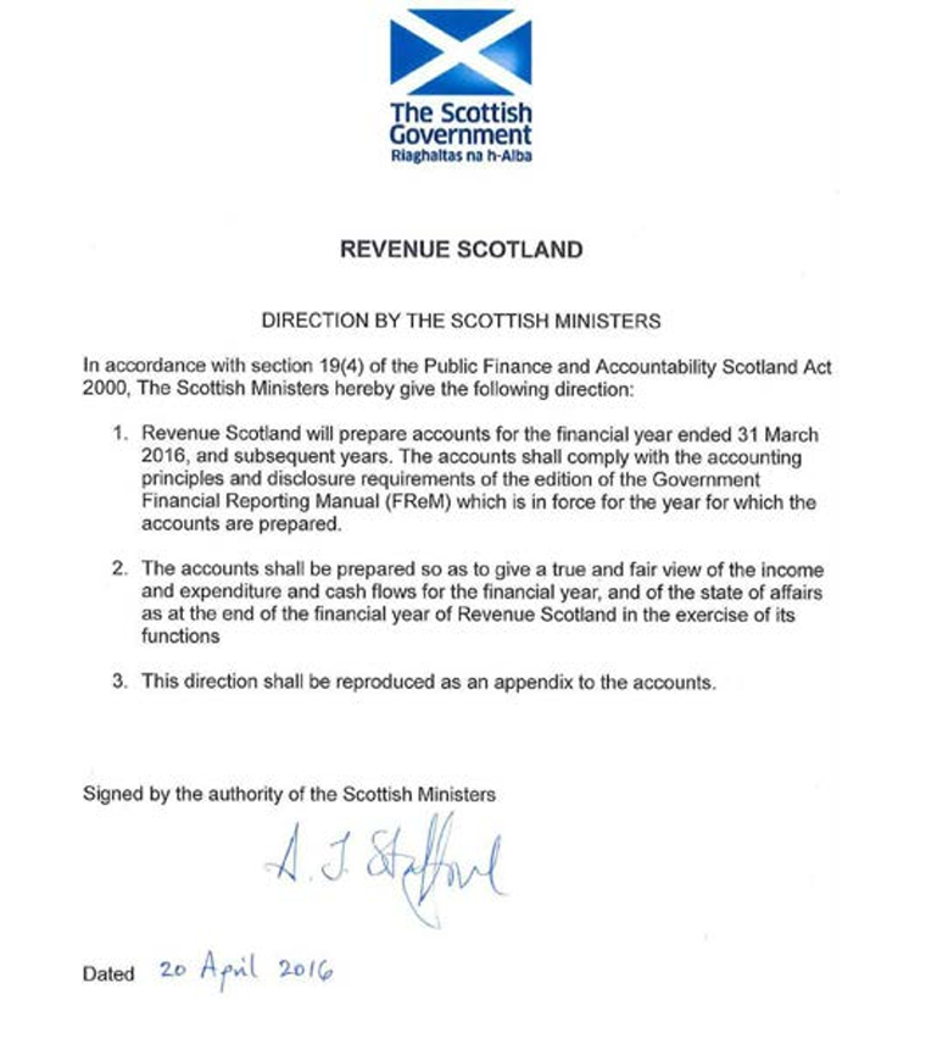
Revenue Scotland
Direction by the Scottish Ministers
In accordance with section 19(4) of the Public Finance and Accountability Scotland Act 2000, The Scottish Ministers hereby give the following direction:
- Revenue Scotland will prepare accounts for the financial year ended 31 March 2016, and subsequent years. The accounts shall comply with the accounting principles and disclosure requirements of the edition of the Government Financial Reporting Manual (FReM) which is in force for the year for which the accounts are prepared.
- The accounts shall be prepared so as to give a true and fair view of the income and expenditure cash flows for the financial year, and the state of affairs as at the end of the financial year of Revenue Scotland in the exercise of its functions
- This direction shall be reproduced as an appendix to the accounts.
Signed by the authority of the Scottish Ministers
A. J. Stafford
Dated 20 April 2016